Perpay - Shop and Build Credit
Perpay Inc.FinanceVerified
- 3.04K Reviews
- 4.8
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
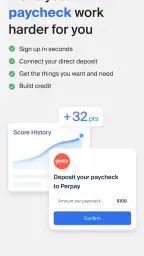
 Analysis by Appwesome
When I consider an app that connects shopping with credit-building, I start with a practical question: does it fit the way I already manage my paychecks, or does it make spending easier than budgeting? Perpay - Shop and Build Credit is a free finance app from Perpay Inc. Its approach is built around purchases paid from a paycheck, so it may appeal to someone who wants a structured alternative to using a conventional credit card. I’d still treat each order as a real commitment, not as extra money to spend.
Cost, value, and the role of paycheck payments
The app is free to download, which makes trying it different from paying a subscription just to access a budgeting tool. That does not, by itself, settle the cost of shopping through it: the price of an item and the schedule for paying for it are what matter when deciding whether a purchase fits. I would compare the full amount and timing with what I could pay elsewhere before ordering, rather than treating free access as proof that every purchase is a bargain.
What the free access does—and does not—mean
For me, the useful distinction is between the app itself and the purchases made inside the shopping experience. Free access lowers the barrier to exploring the service, but it doesn’t make an installment commitment costless. Before choosing an item, I’d check the total I’m agreeing to pay, the amount and timing of each deduction, and whether those deductions leave enough room for ordinary bills. If that information doesn’t feel clear to me at checkout, I’d pause instead of relying on the credit-building idea to justify the purchase.
This is a different value proposition from a free expense tracker. A tracker helps me see where money went; this app is presented as a way to shop and pay over time while building credit. That combination can be useful, but it also means I need to judge both the product and the repayment plan. A purchase I would not make with money already in my account deserves extra scrutiny just because the payments are divided across paychecks.
Where the value can come from
The strongest case is for someone who already needs a particular item, prefers predictable paycheck-based payments, and wants credit-building to be part of the process. In that situation, the value isn’t simply “I can buy now.” It is the possibility of organizing a necessary purchase around a payment rhythm the person can plan for, while making successful payments that the app says are reported to credit bureaus. I would still keep expectations measured: credit progress takes consistent behavior, and it is not a reason to buy something unnecessary.
A realistic example is replacing a household item that has stopped working. I’d first compare the item’s total cost with other ways to buy it, then line the proposed deductions up against rent, utilities, groceries, and the dates those bills are due. If the plan leaves a comfortable margin even in a tighter pay period, the convenience may be worthwhile. If it only works when nothing unexpected happens, I’d wait, save, or choose a less expensive option instead.
How it compares with familiar alternatives
Compared with a standard credit card, the paycheck-based approach may feel more contained because payments are tied to earnings rather than left for me to manage as a separate monthly balance. That structure can help someone who wants fewer moving parts, but it also makes it important to understand what happens to take-home pay after deductions. A card with a low rate or useful terms may be a better fit for someone who already qualifies and can reliably manage its statement.
Other Stories to Read




Compared with a credit-builder product that does not involve shopping, this app puts a purchase at the center of the experience. That makes it more tangible for a person who has a planned need, but less suitable for someone whose priority is improving credit without taking on new spending. If my goal were only to build a record of responsible payments, I’d compare options that don’t require me to buy an item first. I would choose based on the full terms and my own budget, not on the appeal of a single feature.
Small decisions that make the experience safer
One useful habit is to decide on a maximum purchase amount before browsing. Shopping catalogs can make it easy to focus on product features and lose track of the total commitment, so I’d set a limit based on money left after essential expenses. I’d also write down the expected deduction dates and amounts in my regular budget. That simple cross-check helps reveal whether a payment schedule collides with another bill, even if each individual deduction looks manageable.
I’d use the spending limit as a boundary, not a target. A personalized limit may help prevent an order beyond what the service considers appropriate, but it cannot know every upcoming expense or change in my circumstances. For instance, a car repair or a shift in work hours can make a previously comfortable payment harder to handle. Keeping room for those surprises is more valuable than using every available dollar of purchasing capacity.
Another sensible step is to save the purchase details and review them after placing an order. That gives me a quick reference for what I chose and what payments I expect, instead of relying on memory. If I’m considering multiple purchases, I’d look at their combined impact on each paycheck rather than evaluating them one at a time. Several individually small commitments can still leave a tight budget when they overlap.
Who is likely to get the most from it?
I can see this being most useful for a shopper with a specific planned need, a regular paycheck, and enough breathing room to handle deductions without borrowing elsewhere. It may also suit someone who finds a conventional credit card’s revolving balance difficult to track and prefers a purchase-linked payment plan. The key is that the person should be able to afford the item and understand the schedule before committing; credit-building should be an added reason to act carefully, not a substitute for affordability.
I’d be more cautious if income varies substantially, essential bills already consume most of each paycheck, or a person is trying to avoid new purchases altogether. It is also not the first option I’d suggest to someone who can access a lower-cost way to buy the same item and already manages credit comfortably. In those cases, saving in advance or comparing a low-cost card may offer a better balance of flexibility and cost. The right choice depends on the full repayment terms and what the budget can actually sustain.
What to check before relying on credit-building
Before treating any purchase as a credit strategy, I’d make sure I understand the repayment obligations and how successful payments are handled. The app describes reporting successful payments to credit bureaus, but I would not assume that this guarantees a particular score change or timeline. Credit outcomes depend on broader financial circumstances, and paying as agreed is a sound habit whether or not a score moves as quickly as hoped.
I would also ask myself what happens if my paycheck changes or an unexpected expense lands before a deduction. A plan that only works under ideal circumstances is fragile. If I cannot explain how I’d cover the payment during a difficult month without missing essentials, I’d hold off. That is a more useful test than asking only whether an item fits within the displayed limit.
For people who are comparing options, the most important questions are straightforward: What is the complete amount I will pay? When will each payment come out? How does the schedule fit my existing bills? And would I still want this product if it did not contribute to credit-building? If I can answer those clearly and the purchase is genuinely needed, I can judge the offer on its merits rather than its promise.
What is Perpay?
So, what’s the deal with Perpay? At its core, it’s an app that lets you purchase products, pay over time, and simultaneously build your credit score. It’s like having a shopping buddy who’s got your back financially. The idea is to make purchasing and credit-building accessible, especially for those who might not have a stellar credit history.
How It Works
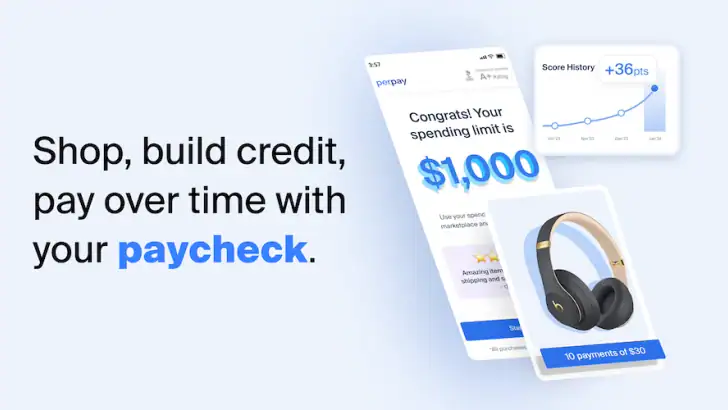
Getting started with Perpay is a breeze. You sign up, and once you’re in, you can browse through a variety of products—from electronics to home goods. Here’s the kicker: you can make these purchases and pay in easy installments directly from your paycheck. The amount is automatically deducted, so you don’t have to worry about missing a payment.
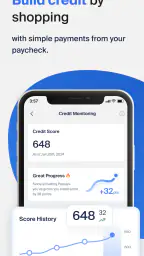
The app reports your successful payments to the credit bureaus, which helps build your credit score over time. It’s a simple yet effective way to improve your credit without the stress of juggling multiple credit cards or loans.
Features I Loved
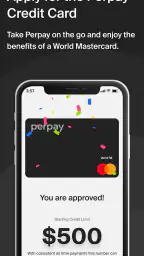
One of the features I found incredibly useful is the personalized spending limit. Perpay evaluates your financial situation and offers a spending limit that aligns with your finances. You’re not tempted to overspend, and it’s all within a budget you can handle.
Another cool feature is the wide range of products available. Whether you’re looking to upgrade your phone or need a new appliance, you’re likely to find it on Perpay. Plus, the app’s interface is super user-friendly, making the whole shopping experience smooth and enjoyable.
Building Credit Without the Stress
What I appreciate most about Perpay is the stress-free way it allows you to build credit. There’s no need to worry about high-interest rates or hidden fees. You see exactly what you’re paying for, and that transparency is refreshing. Over time, as you make your payments, you start to see the positive impact on your credit score.
For someone who’s been trying to rebuild their credit, this was a game-changer. It’s empowering to know that each purchase isn’t just another expense but an investment in your financial future.
Things to Keep in Mind
Like any financial tool, it’s important to use Perpay responsibly. While it’s tempting to go on a shopping spree, remember that it’s still your hard-earned money you’re spending. Staying within your means is key to making the most out of what Perpay offers.
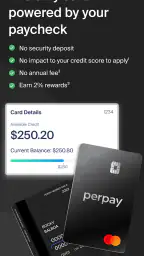
Also, Perpay might not be the best fit for those who can easily qualify for low-interest credit options elsewhere. It’s tailored more for people looking to build or rebuild their credit without the hassle of traditional credit systems.
Final Thoughts
In a nutshell, Perpay - Shop and Build Credit is a solid choice for anyone looking to make essential purchases while simultaneously boosting their credit score. It’s straightforward, reliable, and offers a unique way to manage your finances smartly.
If you’re like me and want to break free from the constraints of a low credit score while shopping for what you need, Perpay might just be the app you’ve been searching for. Go ahead, give it a try, and start your journey towards better credit today!
Who should pause before downloading?
Perpay is a finance app with a 4.8 average from around 8,400 ratings, and it has reached over a million installs. Those numbers suggest that many people have tried it, but they don’t tell me whether its payment structure is right for an individual household. I’d weigh the app’s appeal against my own cash flow, especially if I already have debts or irregular income. A popular service can still be the wrong tool for a particular budget.
The app is rated for everyone, is free, and its current version is 3.6.0; it first appeared on October 19, 2018. It requires iOS 11 or later. These basics make it easier to judge access, but they do not replace reading the purchase and payment details shown during the process. I would download it to assess whether it suits a planned purchase, not as a reason to shop without a plan.
My overall view is that the strongest reason to consider this service is its combination of shopping and paycheck-oriented repayment, not the promise of an instant credit fix. If the product is needed, the total cost is competitive, and the deductions fit comfortably, it can be a practical option to explore. If any of those conditions fail, I’d choose a cheaper purchase route or wait and save. Used with that discipline, it may be helpful; used to stretch a budget, it can make a short-term want feel deceptively manageable.
Highlights
- Easy credit-building with purchases.
- Wide range of products available.
- No credit check required.
- Flexible payment options.
- User-friendly interface.
Limitations
- Limited to U.S. customers.
- Higher prices than competitors.
- Slow customer support response.
- Requires income verification.
- Limited payment flexibility.
Frequently Asked Questions
01What is Perpay and how does it work?
Perpay is a unique financial app designed to help users shop for products while building their credit score. By making purchases through the app, users can pay over time from their paycheck, helping to manage expenses without overspending. It's particularly appealing for those looking to improve their credit history without the need for traditional credit cards.
02How does Perpay help in building credit?
Perpay reports your payment activity to the major credit bureaus. By consistently making timely payments through the app, users can positively impact their credit score. This feature is especially beneficial for individuals with limited credit history, as it provides a practical way to demonstrate financial responsibility.
03What are the pros and cons of using Perpay?
Pros of using Perpay include the ability to shop on a budget, a straightforward payment plan linked to your paycheck, and the potential to improve your credit score. However, cons might include limited product selection compared to larger online retailers and the need for careful budgeting to avoid overspending.
04Is Perpay secure to use for online shopping?
Yes, Perpay prioritizes user security. The app uses encryption and secure payment gateways to protect personal and financial information. Additionally, by linking purchases directly to your paycheck, it minimizes the risk associated with traditional credit card transactions, offering a more controlled way to shop online.
05Are there any fees associated with using Perpay?
Perpay does not charge interest or fees typically associated with credit cards. However, users should be aware of potential late payment fees if they fail to meet their scheduled payments. It's important to review the terms and conditions to understand any possible costs involved with missed payments.


